What Is Tax Diversification and Why Does It Matter in Retirement?
A retirement plan involves more than investments alone.
Let's talk
about how the different pieces of your retirement plan can work together.
Key Takeaways:
- Where your money sits matters as much as how much you've saved. Different accounts are taxed in different ways, so two people with the same balance can end up with very different amounts of spendable income.

- Tax diversification means spreading your savings across three types of accounts. Taxable, tax-deferred, and tax-free accounts each get taxed at a different time, which gives you more control over your taxes in retirement.
- A good mix gives you choices when you need them. You can decide which account to pull from each year to help manage your tax bill, instead of being stuck with one option.
When people picture a comfortable retirement, they usually focus on the size of their nest egg. But how much you’ve saved is only half the story. Where that money sits matters just as much, because different accounts are taxed in different ways, and that changes how much you actually get to spend. In a 2025 Nationwide survey, 59% of retirees said they wish they had prepared better for paying taxes in retirement, and 51% hadn’t thought about how tax rates would affect their income when they first planned.1 Only about 1 in 4 adults work with a financial professional, so a lot of people are sorting this out on their own.2
Once your paycheck stops, retirement is mostly about turning savings into income. If almost all of that money is in one type of account, you’re stuck with that account’s tax rules every time you need cash. Tax diversification gives you more room to move, so you have some say over how your retirement income gets taxed.
Tax Diversification: What It Actually Means in a Retirement Plan
Tax diversification differs from investment diversification, which spreads your money across different investments, like stocks and bonds, to reduce the risk that any one of them drops hard.
Tax diversification, on the other hand, spreads your money across different tax treatments, so you have more than one way to create income after taxes.
While you’re working, taxes mostly shape how you save. In retirement, taxes shape how you spend, because the account you pull from decides how much of each withdrawal you keep. Pull from the wrong one at the wrong time, and you might have to take out more just to cover the same bills.
The Three Tax Buckets That Support Tax Diversification in Retirement
Most tax diversification is built around three broad groups of accounts, often called tax buckets: taxable, tax-deferred, and tax-free. Each can provide income in retirement, but the tax bill hits at a different time for each.
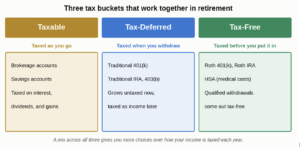
Tax-deferred accounts include traditional 401(k)s, 403(b)s, and traditional IRAs (individual retirement accounts). You contribute money before taxes, it grows without being taxed year to year, and you pay ordinary income tax when you withdraw it in retirement.
The tradeoff is that the tax bill didn’t go away. It just got pushed down the road, and part of that balance actually belongs to the government. So a $500,000 traditional 401(k) isn’t $500,000 of spending money, because some of it goes to taxes when you withdraw it.
These accounts also come with required minimum distributions, or RMDs. Starting at age 73 for most people, the IRS requires you to withdraw a set amount each year, whether you need it or not.3 A large tax-deferred balance can mean big required withdrawals, which push up your taxable income even in years you’d rather keep it low.
Tax-Free Assets: Creating a Source of Income With Different Tax Consequences
Tax-free accounts work the other way around. With a Roth 401(k) or Roth IRA, you put in money you’ve already paid taxes on. It grows tax-free, and as long as you follow the rules, your withdrawals in retirement come out free of federal income tax.
That can matter a lot. Pulling $20,000 from a Roth doesn’t add to your taxable income the way pulling $20,000 from a traditional account does. So you can get the spending money you need without bumping yourself into a higher tax bracket.
A health savings account, or HSA, is another tax-free source worth knowing about. If you use the money for qualified medical costs, those withdrawals are tax-free too, as long as you meet the eligibility and distribution rules.
Taxable Assets: Flexible Money With Its Own Set of Tax Rules
Taxable accounts are things like a regular brokerage account or a savings account. They don’t come with the upfront tax break that retirement accounts do, but they make up for it with flexibility because they aren’t locked behind retirement-withdrawal rules. You can use the money at any age without an early-withdrawal penalty.
Taking money out of a taxable account usually isn’t taxed as ordinary income. Instead, you pay taxes on interest, dividends, or capital gains when you sell something for more than you paid. Your cost basis, what you originally paid, determines how much of a sale counts as taxable gain.
That makes taxable accounts a third source of retirement money, not just a weaker version of a 401(k). They fill gaps the other two buckets can’t.
Why Tax Diversification in Retirement Planning Creates More Flexibility
With all three buckets in play, you can make choices instead of following whatever rules one account hands you. These are the main ways that flexibility shows up in retirement:
- More Control Over Your Year-to-Year Taxable Income: With more than one type of account to draw from, you can choose where your next dollar of spending comes from. Not every withdrawal has to create the same kind of taxable income in the same year.
- Greater Control Over What You Actually Get to Spend: Two accounts with the same balance don't always give you the same spending money. Because a tax-free withdrawal and a taxable one are treated differently, the account you choose affects how much is left after taxes.
- Less Dependence on One Future Tax Rule: If almost everything sits in pre-tax accounts, most of your income is exposed to whatever ordinary income tax rates look like down the road. A broader mix gives you backups if tax rates or your own situation change.
- More Flexibility Around Income Limits: Your taxable income can affect other things in retirement, like how much of your Social Security gets taxed and what you pay for Medicare. Keeping some control over your income can help you stay under the lines that trigger higher costs.
- More Options for Big or Surprise Expenses: Paying for a new roof or a large medical bill all from a tax-deferred account can spike your taxable income for the year. With a few buckets to pull from, you can split the cost across sources and handle it more carefully.
How to Build a Tax Mix That Gives You More Choices Over Time
There’s no magic percentage for how much should sit in each bucket. The right mix depends on what you already have and what income you expect later, like Social Security or a pension. First, review your current accounts and see whether nearly everything falls under one tax treatment.
From there, a few steps can help you shape a better mix over time:
- Look at where your new savings are going while you still have time to adjust. For some people, that means weighing traditional versus Roth contributions at work, or adding to a taxable account for extra flexibility.
- Consider whether moving part of a traditional account into a Roth, called a Roth conversion, makes sense for you. Keep in mind that a conversion counts as taxable income in the year you do it, so timing matters.
- Make use of an HSA if you're eligible, especially if you expect health care to be a big part of your retirement spending.
- Once you're retired, revisit your mix every year instead of following the same withdrawal order forever. Your spending, other income, tax rules, and RMDs can all change which account makes the most sense to tap.
- Remember the point isn't to diversify your taxes just to say you did it. The mix should fit your actual income needs and give you useful choices when tax and cash decisions come up.
Tax Diversification in Retirement FAQs
1. What Is Tax Diversification in Retirement?
It’s spreading your retirement savings across accounts that are taxed in different ways: taxable, tax-deferred, and tax-free. The goal is to give yourself more than one way to create income, so you have some control over your tax bill each year.
2. How Much Should I Have in Taxable, Tax-Deferred, and Tax-Free Accounts?
There’s no one-size-fits-all split. The right mix depends on your income, your tax picture now and later, and what other income you’ll have in retirement. Many people lean heavily on tax-deferred accounts, so adding tax-free and taxable savings can help balance things out.
3. Is It Better to Have Pre-Tax or Roth Money in Retirement?
Neither one wins on its own. Pre-tax money gives you a tax break today, while Roth money gives you tax-free income later. Having both lets you choose which to use depending on your tax situation that year.
4. Can Tax Diversification Lower My Taxes in Retirement?
It can help you manage them. By choosing which account to draw from, you may be able to keep your taxable income lower in a given year, which can affect your tax bracket, your Social Security taxes, and your Medicare costs. It doesn’t erase taxes, but it gives you more control.
5. What Is the Most Overlooked Retirement Tax Break?
One that gets missed a lot is doing Roth conversions in lower-income years, often early in retirement before RMDs and Social Security kick in. Moving money to a Roth during those years can mean paying tax at a lower rate now instead of a higher one later.
6. Can You Improve Your Tax Diversification After You Have Already Retired?
Yes. Even in retirement, you can shift your mix over time, usually through Roth conversions in lower-income years and by being thoughtful about which accounts you pull from first. It’s rarely too late to add some flexibility.
Get Help Creating More Tax Flexibility in Retirement
Retirement tax planning is about more than shaving a little off this year’s tax bill. A healthy mix of taxable, tax-deferred, and tax-free money gives you choices, and those choices get more valuable once your savings have to cover your income for decades.
Goldstone Financial Group can look at how your money is spread across these three tax treatments today and compare that to the income you’ll likely need in retirement. The team’s tax planning work focuses on exactly this kind of coordination, connecting your current mix to your future withdrawals and the taxes that could come with them.
They can also help you line up your contribution choices, possible Roth conversions, and withdrawal decisions so they work with the rest of your retirement plan instead of against it. If you’d like a clearer picture of your own tax mix, you can schedule a complimentary consultation with Goldstone Financial Group.
Resources: