September 11, 2026 Market Recap & Outlook: Hot Core Inflation Puts the Hike at 90%. And the Houthis Seize the Red Sea’s Gate.
A retirement plan involves more than investments alone.
Let's talk
about how the different pieces of your retirement plan can work together.
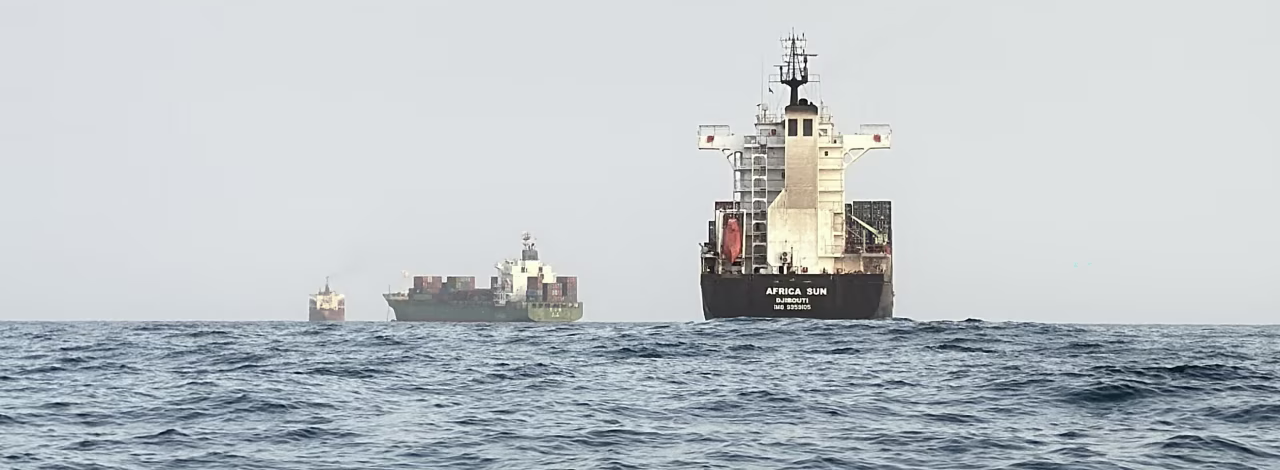
Image credit: Wall Street Journal
The September 11, 2026 Market Recap & Outlook takes a closer look at a week shaped by hotter inflation, rising interest rate expectations and renewed pressure on global energy markets. With core inflation coming in above forecasts, markets pushed the probability of a September Federal Reserve rate hike to nearly 90%, while escalating conflict around critical Red Sea shipping routes helped send Brent crude above $100. Stocks, bonds, gold and Bitcoin all finished the week lower, underscoring how quickly changing rate expectations and geopolitical developments can ripple across markets.
In this week’s Market Recap & Outlook, Matthew Rice, CFA, CAIA, Chief Investment Officer at Goldstone Financial Group, examines the key economic events, market performance, and investment themes that shaped the week and what investors should watch in the days ahead.
Market Recap & Outlook
Your Weekly Market Compass – September 11, 2026
The last inflation reports before the Federal Reserve’s decision broke the hawks’ way, with core CPI running hotter than forecast and producer prices up 5.4% year over year, driving the odds of a rate hike this week to nearly 90%. Halfway around the world, Iran’s Houthi allies completed a lightning capture of Yemen’s Red Sea coastline, seizing the Bab el-Mandeb gateway that had carried Saudi oil around the Hormuz blockade, and Brent finished above $100 after its strongest week since the war’s opening act. Stocks, bonds, gold, and Bitcoin all fell together.
The week answered its own question. For a month, markets have debated whether the Federal Reserve would deliver its first rate increase of 2026 at the September 15-16 meeting; by Friday afternoon, fed funds futures had all but settled it. Thursday’s producer price index rose 0.4% with the annual rate at 5.4%, driven by a 4.2% energy surge, and Friday’s consumer price index landed the decisive blow: headline inflation of 0.4% for the month and 3.4% for the year matched forecasts, but core CPI rose 0.3%, a tenth hotter than expected, and gasoline alone, up 3.9% in August, accounted for over a third of the monthly increase. CME FedWatch odds of a quarter-point hike jumped from 71% to nearly 90%, with the odds of a second hike at the October meeting priced near 60%. The same Friday, the war handed the inflation problem a new supply line: Houthi forces completed their capture of Yemen’s entire Red Sea coastline, seizing the Bab el-Mandeb gateway that had become the alternative route for Saudi oil, while strikes forced Saudi Arabia to shut its East-West pipeline. Brent gained 8.7% for the week to close above $100. Nothing was spared: stocks fell with small caps down 2.4%, bonds suffered their worst week in months with the Aggregate off 1.0%, gold dropped 2.0%, and Bitcoin slid 5.8%.
Selling everything at once is the signature of a rising discount rate, and that is precisely what happened: the market stopped trading growth versus recession and started trading the cost of money itself. This week delivers the verdict, with the Fed’s decision Wednesday, a Tehran-Gulf states meeting in Oman that briefly knocked oil back on Friday, and a bond market that has already done much of the committee’s tightening for it.
Inflation & the Fed
The Deciders Decide: Hot Core CPI Locks the Market Onto a Hike
The two reports the Fed was waiting for arrived, and together they closed the argument the July dissenters started. Thursday’s PPI rose 0.4% for the month, in line with forecasts, but the year-over-year rate of 5.4% ran a tenth above expectations, powered by a 4.2% jump in energy, and lifted hike odds into the high 60s. Friday’s CPI finished the job: the headline’s 0.4% monthly and 3.4% annual readings matched consensus, but core inflation’s 0.3% monthly gain exceeded the 0.2% forecast, with the annual core rate at 2.4%. The BLS noted gasoline’s 3.9% August rise accounted for over a third of the total monthly increase, with technology, airfare, and communication prices also jumping, and all of it predates the fresh oil surge now underway. Within minutes, CME FedWatch odds of a September hike leapt from 71% to nearly 90%, the two-year Treasury yield rose to 4.594%, and the odds of another quarter-point hike in October reached almost 60%.
Geopolitical Watch & Energy Markets
The Second Gate Falls: Houthis Take the Bab el-Mandeb
While Washington watched inflation, Iran’s allies redrew the map of oil logistics. In a rapid offensive that analysts called the most significant regional development since the war began in February, Houthi forces seized the port city of Mokha on Thursday and by Friday had effectively completed control of Yemen’s entire Red Sea coastline, including the island of Mayun in the Bab el-Mandeb Strait, the chokepoint through which roughly 12% of the world’s goods typically pass. The strait had become the critical alternative for Saudi oil exports since Iran’s blockade of Hormuz, and the same Friday, Saudi Arabia shut its East-West pipeline, the cross-country artery vital to those rerouted exports, as a precaution after drone attacks its foreign ministry said originated from Iraq. The Houthis declared maritime navigation safe for all companies except Saudi vessels, vowing escalation for escalation; Saudi Crown Prince Mohammed bin Salman is reported to be urging President Trump toward military action; and the United Nations warned Yemen is sliding back toward all-out war, with more than 46,000 people displaced in a week.
Oil traded the geography. Brent surged through the week to settle near $108 on Thursday, its highest in nearly four months, before Friday brought the war’s now-familiar counterpoint: Iranian state media said Tehran will meet Gulf states in Oman to discuss the Strait of Hormuz, and crude fell nearly 3% on the diplomacy signal, with WTI settling at $99.66. Even after the pullback, Brent finished the week up 8.7% and above $100, with WTI up 9.4%, and a Wall Street Journal report that White House advisers have discussed the possibility of hostilities extending beyond the President’s current term underscored how far expectations have shifted from the quick resolution markets priced in the spring.
Why the Bab el-Mandeb Matters Now: Since February, the war’s economic logic has run through one chokepoint; as of Friday it runs through two. Hormuz remains blockaded and contested, and the Red Sea route that partially replaced it now has an Iranian-aligned force holding its southern gate and openly targeting Saudi shipping, while the pipeline built to bypass sea routes altogether sits shut after attacks from a third direction. Saudi Arabia’s three paths to market have all been impaired in the same week, which is why crude’s move above $100 carried a different quality than July’s spike: this one reprices the system’s redundancy, not just its risk. The Oman meeting is now the single most important diplomatic event on the calendar, because it is the first that involves the Gulf states whose oil, and whose waters, the conflict has fully engulfed.
Performance Data
Market Snapshot — Week Ending September 11, 2026
Nothing worked. Small caps fell hardest, down 2.4%, with mid caps off 1.7%, and the S&P 500’s 0.8% decline was the gentlest outcome in domestic equities. Bonds offered no refuge: the Aggregate fell 1.0% and is now down 1.4% for the year, municipals dropped 1.0% in their second hard week, TIPS lost 1.0%, and the 20+ Year Treasury index fell 1.6%. Gold surrendered 2.0% and Bitcoin 5.8%. The exception, again, was emerging markets, off just 0.2%, a resilience that has now carried the segment to the top of the 2026 leaderboard at +24.3%, overtaking small-cap value for the first time since spring.
| Index | Last Week | YTD 2026 |
|---|---|---|
| Fixed Income & Alternatives — Total Return | ||
| Bloomberg US Treasury Bills 1–3 Month | 0.0% | +2.6% |
| Bloomberg US Government/Credit 1–3 Year | −0.4% | +0.8% |
| Bloomberg US Aggregate | −1.0% | −1.4% |
| Bloomberg Municipal 1–15 Year | −1.0% | −1.5% |
| Bloomberg Municipal Bond High Yield | −1.2% | +1.1% |
| Bloomberg US TIPS (Series-L) | −1.0% | −0.4% |
| Bloomberg Global Aggregate | −0.8% | −0.9% |
| Bloomberg US Corporate High Yield | −0.5% | +2.0% |
| ICE US Treasury 20+ Year Total Return | −1.6% | −4.4% |
| S&P/TSX North American Preferred Stock | −0.5% | +4.8% |
| SPDR Gold Shares (GLD) | −2.0% | +0.6% |
| Invesco DB US Dollar Index (UUP) | 0.0% | +3.8% |
| Bitcoin Price Return | −5.8% | −13.4% |
| Global Equity — Total Return | ||
| MSCI ACWI IMI Net Total Return | −1.0% | +13.9% |
| MSCI ACWI Net Total Return | −0.9% | +13.8% |
| Russell 3000 Total Return | −0.9% | +12.8% |
| S&P 500 Total Return | −0.8% | +12.8% |
| Russell 1000 Value Total Return | −0.8% | +22.5% |
| Russell 1000 Growth Total Return | −0.9% | +3.7% |
| Russell Midcap Total Return | −1.7% | +14.8% |
| Russell Midcap Value Total Return | −1.9% | +19.3% |
| Russell Midcap Growth Total Return | −1.2% | +1.1% |
| Russell 2000 Total Return | −2.4% | +18.0% |
| Russell 2000 Value Total Return | −2.1% | +22.3% |
| Russell 2000 Growth Total Return | −2.6% | +14.0% |
| MSCI EAFE Net Total Return | −1.4% | +12.5% |
| MSCI Emerging Markets Net Total Return | −0.2% | +24.3% |
| S&P 1500 Real Estate (Sector) | −1.2% | +10.4% |
Source: Goldstone Investment Research; data through September 11, 2026 close. All returns are total return unless otherwise noted. Index return data sourced from Goldstone Financial Group internal data systems as of September 11, 2026 close. GLD and UUP reflect fund net asset value performance. Bitcoin year-to-date return calculated from December 31, 2025 close ($88,414.63) to September 11, 2026 close ($76,554.99). The Houthis’ weekend consolidation and pre-FOMC positioning occurred September 12-13, after the close of the period covered. Past performance is not indicative of future results. For long-term investors, reacting to short-term bond-market losses by reducing fixed-income exposure can crystallize losses and may reduce the opportunity to benefit from higher reinvestment yields.
Looking Ahead
Key Events: Week of September 14, 2026
The waiting ends. The Federal Reserve’s two-day meeting concludes Wednesday with the most anticipated rate decision in years, and the Gulf’s first multilateral diplomacy since the Red Sea’s fall convenes in Oman.
Weekly Summary
What It All Means for Investors
The week stripped the September question of its suspense and replaced it with a harder one: not whether the Fed hikes, but whether one hike, or two, into a war-driven oil shock lands on an economy that can absorb it. The market’s answer on Friday was sober rather than panicked, with the S&P 500 down less than 1% for the week even as the bond market repriced sharply, but the breadth of the decline, with every major asset class falling together, showed what a rising cost of money does to a portfolio in the short run. It also showed, in emerging markets’ near-flat week and year-to-date leadership, that the diversification argument survives even weeks designed to defeat it.
Two changes on the year’s scoreboard deserve notice. Emerging markets, at +24.3%, now lead 2026, the first leadership change since spring, having outpaced every domestic segment through a quarter in which the dollar’s direction, the war’s geography, and the Fed’s path all shifted repeatedly. And the bond market’s repricing, painful as this week was, has rebuilt the compensation that vanished in the spring: short Treasuries yield near their cycle highs, TIPS carry positive real yields, and municipals sit at their cheapest levels of the year. For long-term investors, reacting to short-term bond-market losses by reducing fixed-income exposure can crystallize losses and may reduce the opportunity to benefit from higher reinvestment yields.
Wednesday will be loud whatever it brings. A hike at 90% odds is mostly in the price, which means the market’s reaction will key off the dissents, the projections, and the chairman’s October guidance rather than the move itself; a hold would unleash the year’s biggest single-day repricing. We take no position on which it will be. Our portfolio approach remains focused on diversification across asset classes and market segments and disciplined rebalancing based on each strategy’s objectives rather than short-term market forecasts. Which is anchored to the observation that has held through seven months of war, which is that the investors hurt worst in 2026 have consistently been the ones who acted on a forecast.
A week in which stocks, bonds, gold, and Bitcoin all fell together is exactly when process matters most. most. GoldstoneBuilder™ is designed to construct diversified portfolios across multiple asset classes, investment styles, market capitalizations, and geographic regions based on a client’s objectives and risk profile. GoldstoneBalancer™ helps keep your allocation aligned with your long-term objectives as the Fed’s decision, the Oman talks, and the Red Sea’s new reality unfold. Clients with questions about their fixed income positioning after the yield reset, or their portfolio into Wednesday’s decision, are encouraged to reach out directly to their Goldstone advisor.
Disclosure:
Goldstone Financial Group, LLC (“GFG”) is a registered investment advisor with the U.S. Securities and Exchange Commission. Registration does not imply a certain level of skill or qualification. This material is provided for informational purposes only. Opinions expressed herein are solely those of GFG. None of the information presented in this material is intended to offer personalized investment advice and does not constitute an offer to sell or solicit any offer to buy a security or any insurance product, and is not intended to be used as the sole basis for financial decisions, nor should it be construed as advice designed to meet the particular needs of an individual’s situation. You cannot invest directly in an index, and those do not reflect the deduction of investment advisory fees or other expenses that would reduce the returns experienced by an investor. Any index or benchmark performance figures are for comparison purposes only, and client or strategy holdings will not directly correspond to any such data. Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment will either be suitable or profitable for your portfolio. All investment strategies have the potential for profit or loss and past performance is no guarantee of future success. Historical performance results for investment indexes and/or categories, generally do not reflect the deduction of transaction and/or custodial charges or the deduction of an investment-management fee, the incurrence of which would have the effect of decreasing historical performance results. Diversification and asset allocation do not assure a profit or protect against loss. Economic factors, market conditions, and investment strategies will affect the performance of any portfolio and there are no assurances that it will match or outperform any particular benchmark. Index performance is provided for illustrative purposes and does not reflect the performance of any client account.
This communication is for informational purposes only and does not constitute investment advice, a solicitation, or an offer to buy or sell any security. Past performance is not indicative of future results. Investing involves risk, including the possible loss of principal. The views expressed herein reflect those of Goldstone Financial Group as of the date of publication and are subject to change without notice. Index returns shown are total return unless otherwise noted and are not available for direct investment. All index return data sourced from Goldstone Financial Group internal data systems as of August 7, 2026 close. GLD and UUP reflect fund net asset value performance. Bitcoin figures reflect the most recent close available in Goldstone data systems, August 6, 2026 ($64,608.71); year-to-date return calculated from December 31, 2025 close ($88,414.63). July employment report data sourced from the U.S. Bureau of Labor Statistics, CNBC, Reuters, and Babypips, released August 7, 2026. September rate hike probability sourced from the CME FedWatch tool via CNBC and Kiplinger, August 7, 2026. U.S.-Iran negotiations, Iran-Oman safe-passage talks, and Strait of Hormuz developments sourced from CNN, CNBC, Fox News, and The National, August 3-9, 2026. Oil price data sourced from CNN and The National, August 3-8, 2026. Retail gasoline price data sourced from AAA, July 2-30, 2026. Gold and silver price data sourced from Reuters via ARY News, TheStreet, and Trading Economics, August 7, 2026. Palantir results and earnings season statistics sourced from TheStreet, Seeking Alpha, and FactSet via CNBC, August 3-7, 2026. The Vance remarks on the Hormuz traffic scheme and Iran’s push for concessions occurred August 8-9, 2026, after the close of the trading period covered in this recap. Clients should consult with their Goldstone Financial Group advisor regarding their specific circumstances before making any investment decisions.